THE KEY TAKEAWAYS
- 01
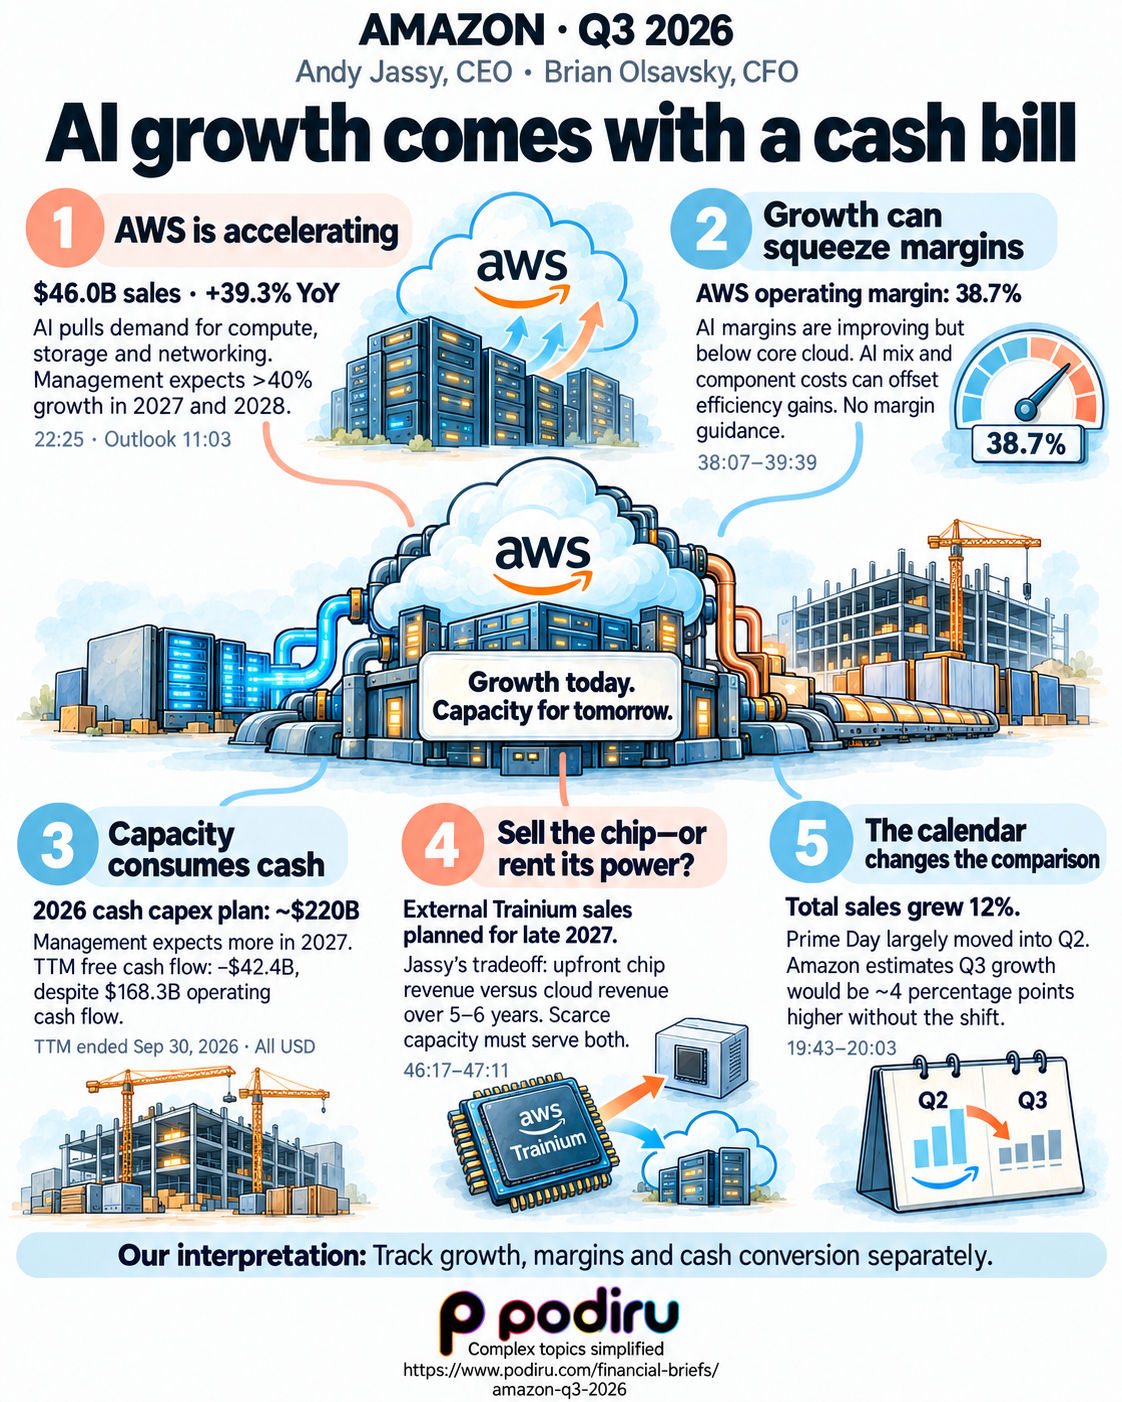
AWS is accelerating
$46.0B in sales, up 39.3% year over year. AI also pulls demand for compute, storage and networking. Management expects AWS growth above 40% in 2027 and 2028.
- 02
Growth can squeeze margins
AWS operating margin was 38.7%. AI margins are improving but remain below core cloud. AI mix and component costs can offset efficiency gains. Amazon gave no AWS margin guidance.
- 03
Capacity consumes cash
The calendar-2026 cash-capex plan is about $220B; management expects more in 2027. For the trailing twelve months ended September 30, free cash flow was −$42.4B despite $168.3B in operating cash flow. These are different periods, not a direct subtraction.
- 04
Sell the chip—or rent its power?
External Trainium sales are planned for late 2027. Jassy describes a tradeoff between upfront chip-sale revenue and cloud revenue over five to six years. Scarce manufacturing capacity must serve both.
- 05
The calendar changes the comparison
Total sales grew 12%. Prime Day largely moved into Q2. Amazon estimates Q3 growth would have been about four percentage points higher without the shift.
Our interpretation
Track growth, operating margins and cash conversion separately.
Sources & context
Five takeaways from Amazon’s full Q3 2026 earnings call with CEO Andy Jassy and CFO Brian Olsavsky, cross-checked against its official release. The public call transcript reference is provided by Quartr via StockAnalysis.
- Official earnings release and financial tables ↗
- Public call transcript reference · Quartr via StockAnalysis ↗
- USD; growth comparisons are year over year unless labeled.
- The calendar-2026 capital-spending plan and trailing-twelve-month cash flows cover different periods.
- Future growth, spending and product-launch statements are management expectations, not guaranteed outcomes. Amazon supplied no AWS margin guidance.
- Podiru interpretation, not an investment recommendation.
Checked October 29, 2026.