THE KEY TAKEAWAYS
- 01
Profit has two layers
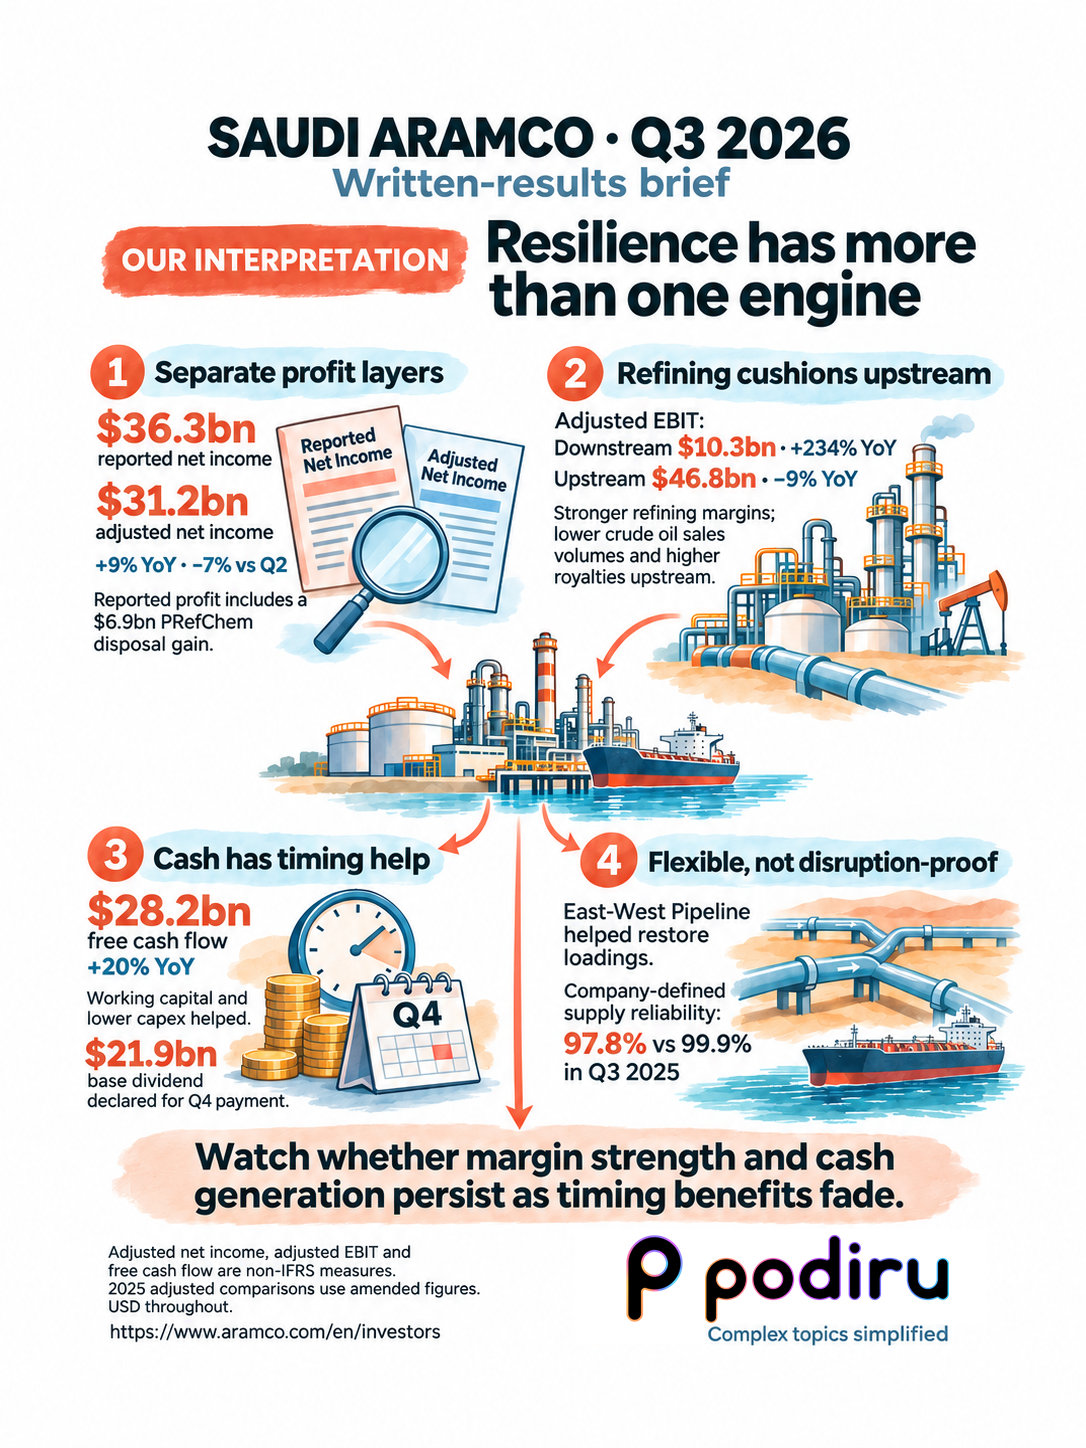
Reported consolidated net income was $36.3bn, including a $6.9bn PRefChem disposal gain. Adjusted net income was $31.2bn, up 9% year over year but down 7% from Q2. The disposal gain is not cash proceeds or the complete bridge from reported to adjusted income.
- 02
Refining cushioned upstream
Downstream adjusted EBIT rose 234% year over year to $10.3bn as stronger refining margins helped. Upstream adjusted EBIT fell 9% to $46.8bn, weighed down by lower crude oil sales volumes and higher royalties. Segment EBIT and consolidated net income are different measures.
- 03
Cash had timing help
Free cash flow rose 20% to $28.2bn: operating cash flow of $38.727bn less capital expenditure of $10.524bn. Favorable working capital and lower capex helped. Those timing benefits may not persist. The $21.9bn base dividend was declared for Q4 payment, not an amount paid during Q3 or a guarantee of future coverage.
- 04
Routes helped; reliability slipped
Export flexibility, including the East-West Pipeline, helped restore loadings. Company-defined supply reliability was 97.8%, versus 99.9% in Q3 2025. It measures committed product volume delivered within 24 hours of schedule, excluding delays beyond company control. It is not uptime, a safety score or proof of zero disruption.
- 05
Keep subsequent events separate
Zuluf began production in October, after quarter-end. The 49% HUMAIN transaction closed November 1 and involved roughly $2.6bn in cash plus AI assets. HUMAIN is accounted for as an associate. These are subsequent events, not Q3 operating results or evidence of AI monetization.
Our interpretation
Our interpretation: refining strength and alternative export routes helped absorb shocks. Watch whether margins and cash generation persist as working-capital benefits fade.
Sources & context
Based on the complete official 44-page Q3 and nine-month interim report and two-page results release. This is a written-results brief, not a review of the earnings call or Q&A.
- Q3 and nine months 2026 interim report ↗
- Q3 2026 results release ↗
- Aramco investor overview and Q3 2026 results ↗
- Written-report edition based on official interim report and release; no earnings-call or Q&A review claimed.
- Quarter ended September 30, 2026. Reported net income is consolidated, not shareholder-attributable.
- USD values are convenience translations at SAR 3.75 per USD. Figures are rounded for the visual brief.
- Adjusted net income, adjusted EBIT and free cash flow are company-defined non-IFRS measures. 2025 adjusted comparisons use amended figures.
- PRefChem disposal gain is not cash proceeds and is not the complete reported-to-adjusted income reconciliation.
- Free cash flow is operating cash flow less capex: $38.727bn − $10.524bn = $28.203bn. Working-capital and capex timing benefits may not persist.
- The $21.9bn base dividend was declared for Q4 payment, distinct from dividends paid during Q3; the map does not establish future coverage.
- Supply reliability is company-defined committed product volume delivered within 24 hours of schedule, excluding delays beyond company control. It is not uptime, safety, or proof of zero disruption.
- Zuluf October start and November 1 HUMAIN closing are subsequent events, not Q3 operating results. HUMAIN is accounted for as an associate; no AI monetization outcome is established.
- Financial statements are unaudited interim statements with a PwC review, not an audit opinion.
- Original Podiru interpretation, not an investment recommendation.
Checked November 3, 2026.