THE KEY TAKEAWAYS
- 01
A stronger quarter
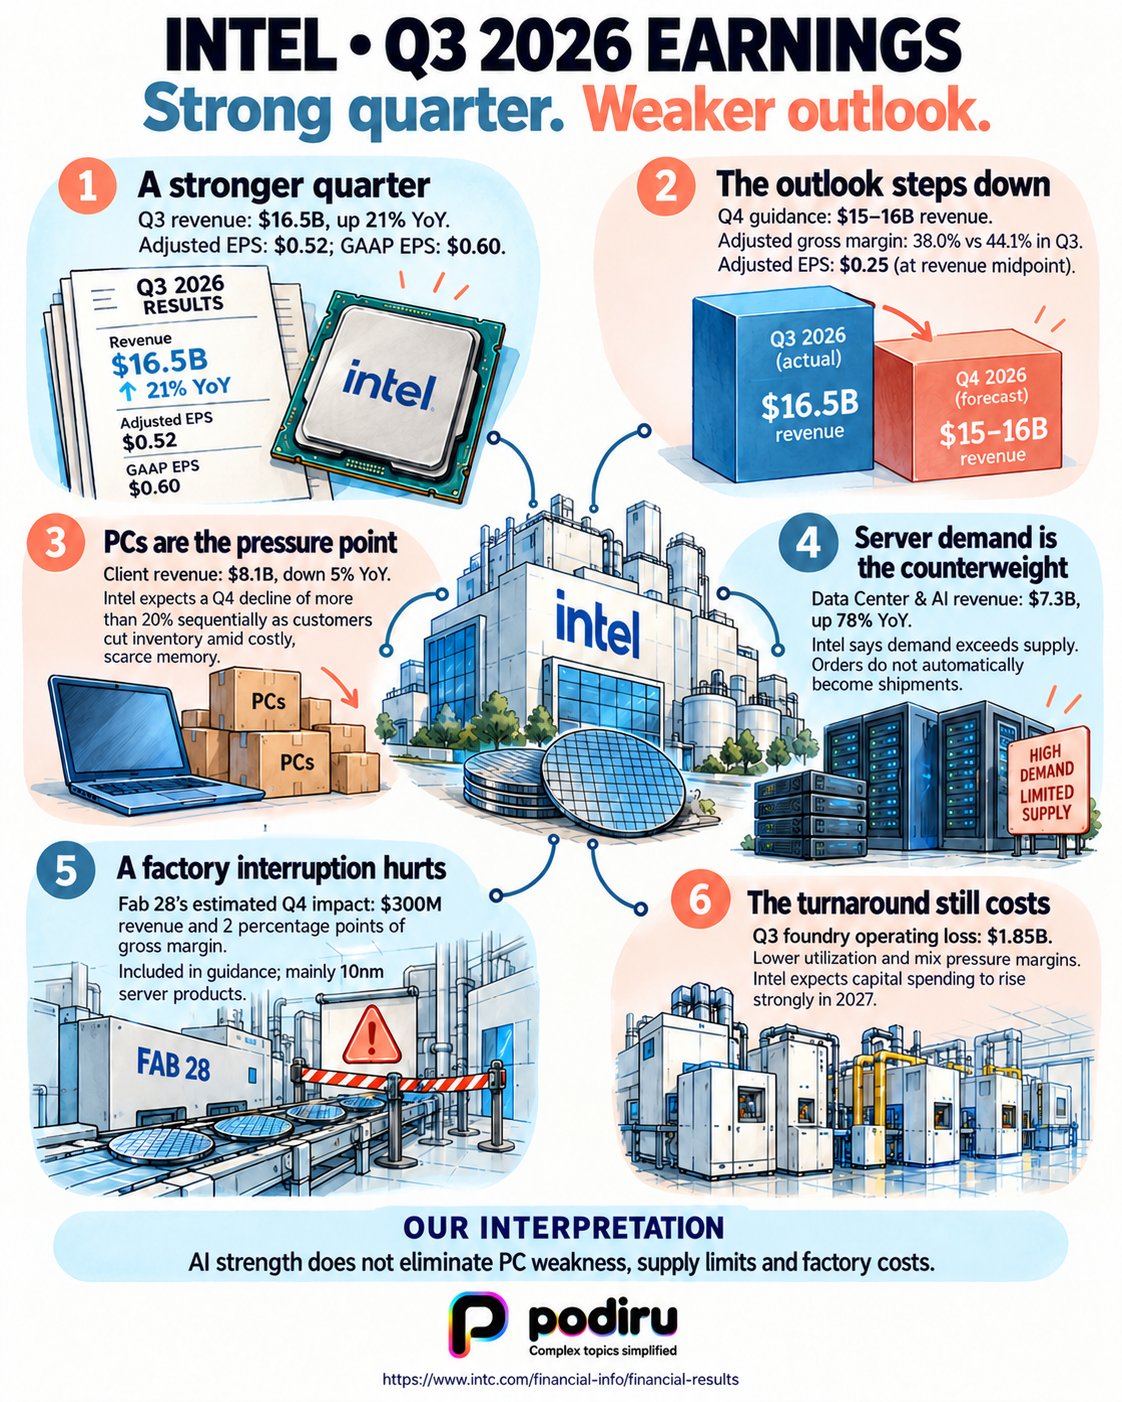
Q3 revenue was $16.5B, up 21% year over year. Adjusted earnings per share were $0.52; GAAP earnings per share were $0.60. These are different measures.
- 02
The outlook steps down
Intel forecasts Q4 revenue of $15–16B. Adjusted gross margin guidance is 38.0%, versus 44.1% in Q3. Adjusted EPS guidance is $0.25 at the revenue midpoint. These are forecasts, not reported Q4 results.
- 03
PCs are the pressure point
Client revenue was $8.1B, down 5% year over year. Intel expects Q4 client revenue to decline more than 20% sequentially as customers reduce inventory and expensive, scarce memory weighs on demand.
- 04
Server demand is the counterweight
Data Center & AI revenue was $7.3B, up 78% year over year. Intel says demand exceeds supply. Strong orders do not automatically become shipments when capacity is constrained.
- 05
A factory interruption hurts
Intel estimates Fab 28 will affect Q4 revenue by $300M and gross margin by two percentage points, mainly involving 10nm server products. Those estimated effects are already included in guidance; they are not an additional deduction.
- 06
The turnaround still costs
Foundry recorded a Q3 operating loss of $1.85B. Low utilization and product mix pressure margins. Intel expects capital spending to rise strongly in 2027.
- 07
Put the stock move in context
At 9:11 a.m. EDT on October 30, a premarket snapshot showed $68.20, down 25.93% from the $92.07 prior close. This is a timestamped observation, not a live quote or proof of a single cause. Our interpretation: the weaker outlook, PC slowdown and factory costs help explain investor concerns despite stronger Q3 results.
Our interpretation
AI strength does not eliminate PC weakness, supply limits and factory costs.
Sources & context
Based on Intel’s complete official Q3 earnings release, prepared remarks and presentation. This is a report-based brief, not a review of the full call or Q&A. The stock-price observation is a premarket snapshot from October 30 at 9:11 a.m. EDT.
- Official earnings release and financial tables ↗
- Official Q3 prepared remarks ↗
- Official Q3 earnings presentation ↗
- Intel financial results archive ↗
- StockAnalysis · source of the timestamped premarket snapshot ↗
- USD; growth comparisons are year over year unless labeled sequential. The fiscal quarter ended September 26, 2026.
- Adjusted measures are non-GAAP. Intel’s release provides reconciliations; they do not replace GAAP results.
- Q4 guidance and 2027 spending expectations are forward-looking. Estimated Fab 28 effects are already included in Q4 guidance.
- The 25.93% stock decline is a timestamped premarket observation, not a current quote. The sources do not establish an exact 28% decline or a single cause.
- Podiru interpretation, not an investment recommendation.
Checked October 30, 2026.