THE KEY TAKEAWAYS
- 01
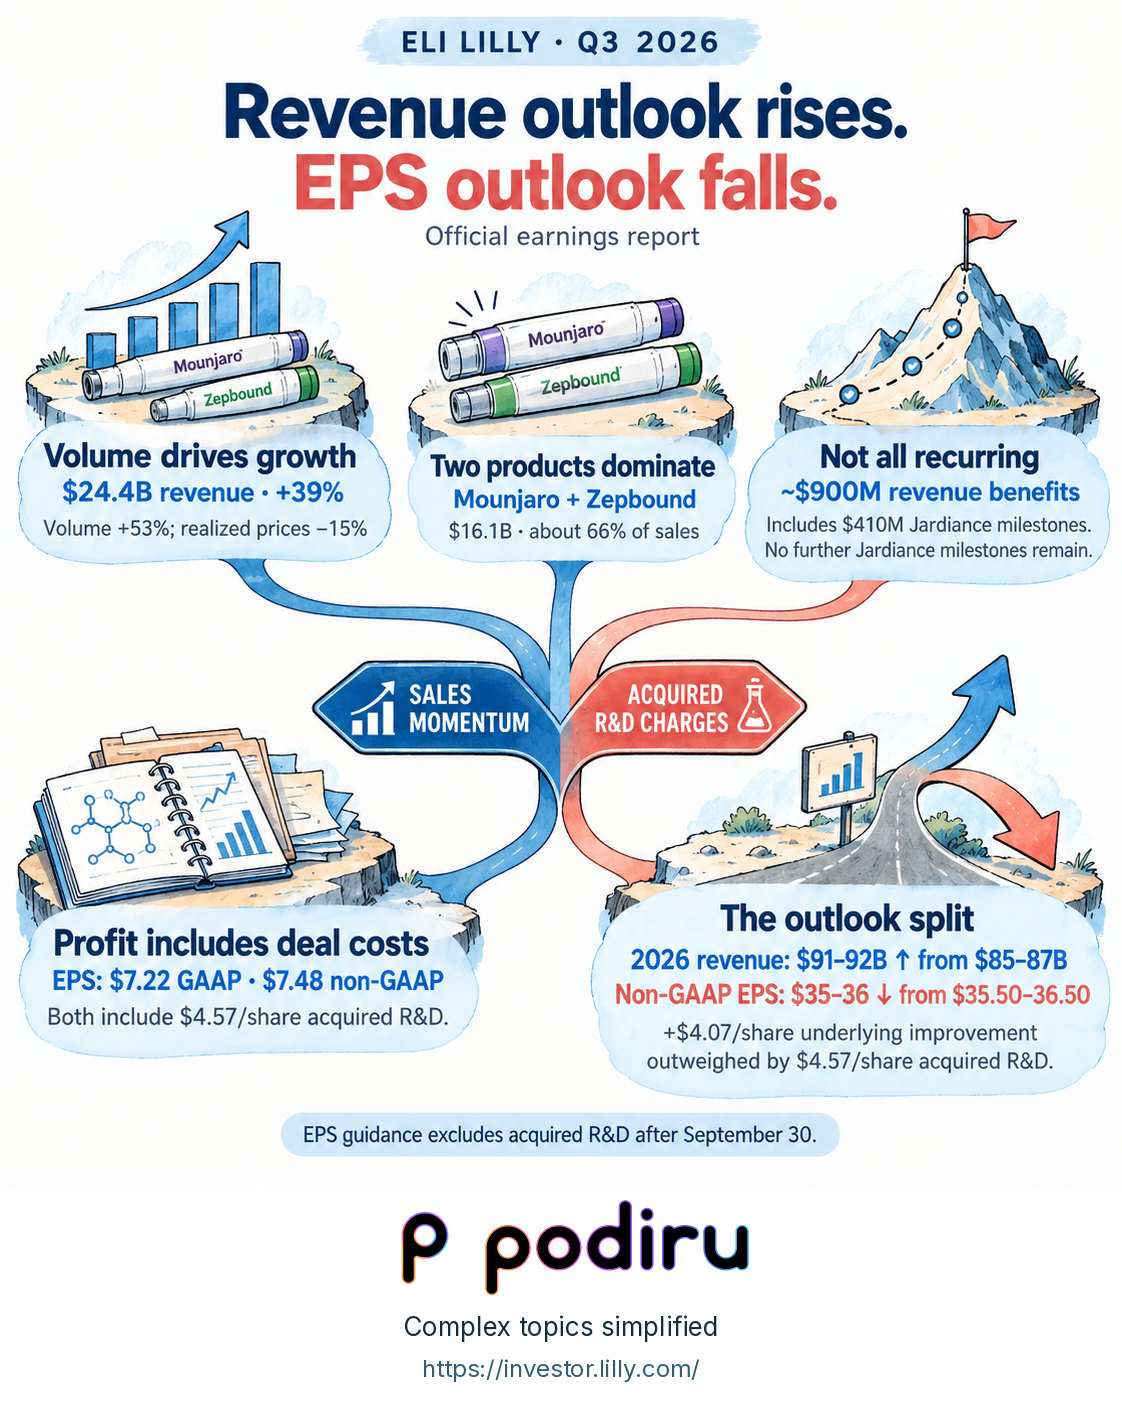
Volume drives growth
Revenue $24.4B, up 39%. Volume +53% offsets realized prices −15%.
- 02
Two products dominate
Mounjaro + Zepbound: $16.1B, about 66% of sales.
- 03
Not all recurring
About $900M of revenue benefits, including $410M from Jardiance milestones. No further Jardiance milestones remain.
- 04
Profit includes deal costs
EPS: $7.22 GAAP; $7.48 non-GAAP. Both include $4.57/share of acquired R&D charges.
- 05
The outlook split
2026 revenue: $91–92B, up from $85–87B. Non-GAAP EPS: $35–36, down from $35.50–36.50. Underlying +$4.07/share improvement was outweighed by $4.57/share acquired R&D charges.
Our interpretation
Acquired R&D charges outweigh the underlying improvement in the EPS outlook, even as sales guidance rises.
Sources & context
Based on the complete official Lilly Q3 earnings release and appended financial tables. This report-based brief does not claim full-call, Q&A or 10-Q review.
- USD; growth comparisons are year over year. The quarter ended September 30, 2026.
- Non-GAAP EPS is distinct from GAAP EPS; both include the acquired R&D charges shown.
- 2026 guidance is a forecast. EPS guidance excludes acquired R&D charges incurred after September 30.
- Podiru interpretation, not an investment recommendation.
Checked October 30, 2026.