THE KEY TAKEAWAYS
- 01
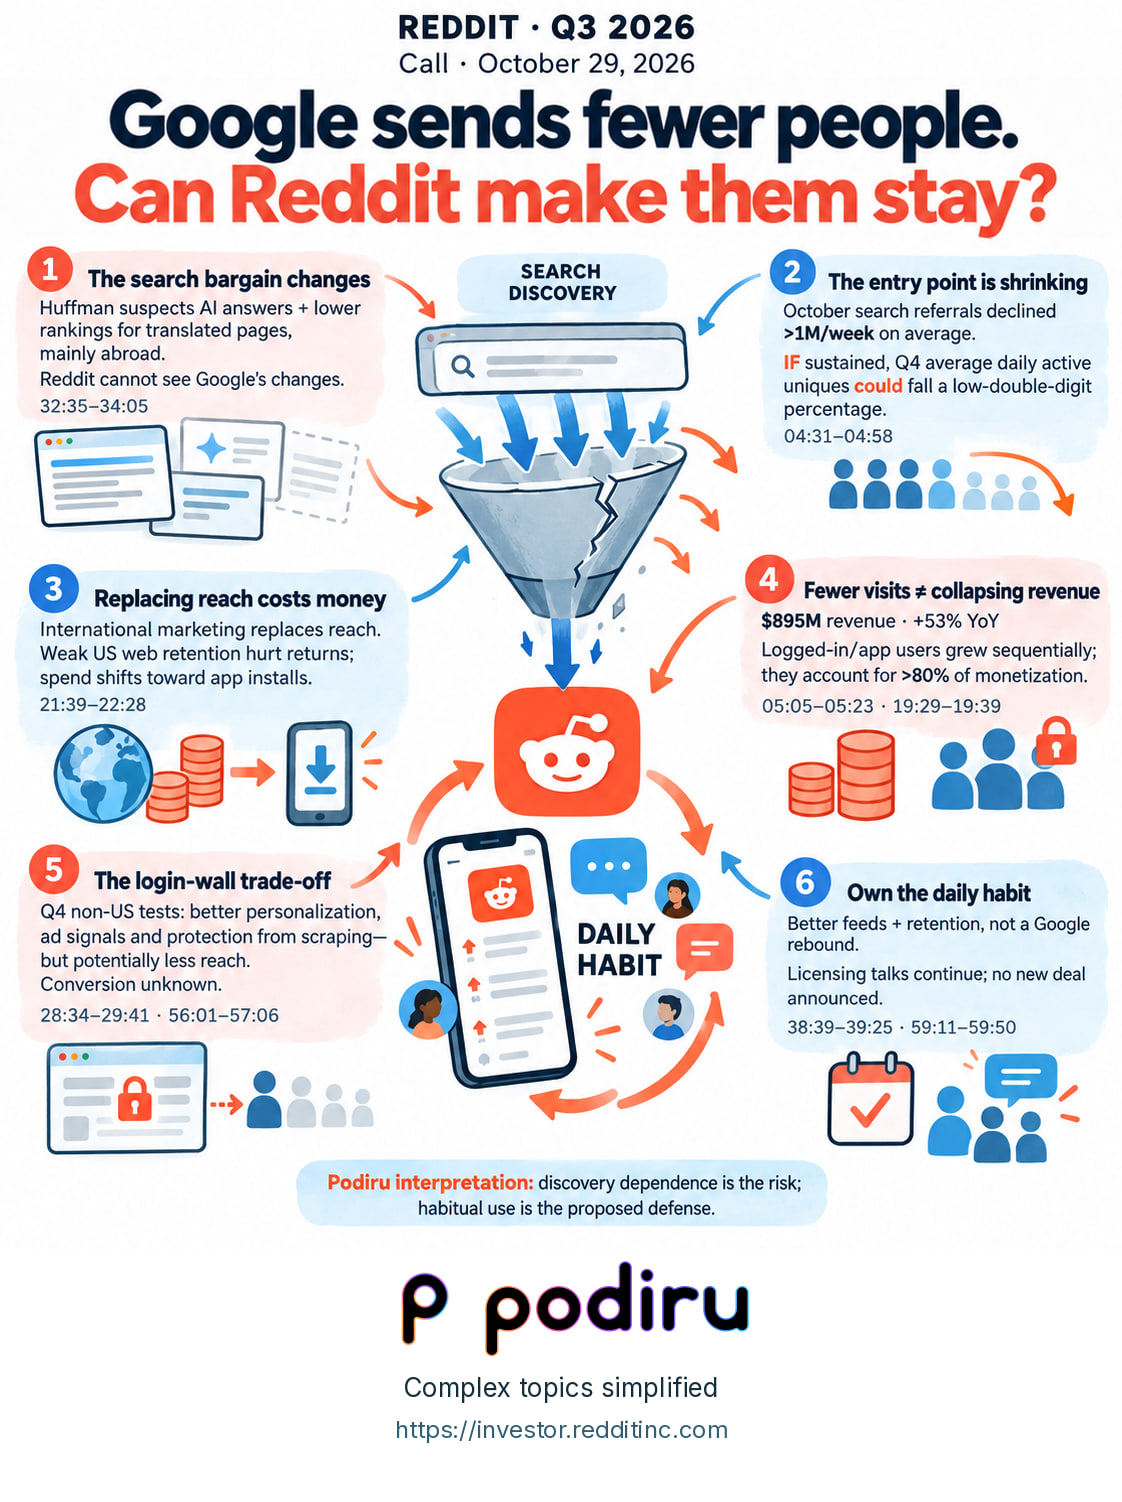
The search bargain changes
Huffman's hypothesis: AI answers crowd out links; translated Reddit pages rank lower, mainly abroad. Reddit lacks visibility into Google's changes. (Call audio 32:35–34:05).
- 02
The entry point is shrinking
October search referrals fell by over 1 million per week on average. If that pace persists, Q4 daily active uniques could fall a low-double-digit percentage. (Call audio 04:31–04:58).
- 03
Replacing reach costs money
More international marketing offsets lost search reach. US web campaigns brought users—but weak retention hurt returns. Spend is shifting toward app installs. (Call audio 21:39–22:28).
- 04
Fewer visits ≠ collapsing revenue
Q3 revenue: $895m, +53% YoY. Logged-in/app users grew sequentially and account for over 80% of monetization. (Call audio 05:05–05:23 · 19:29–19:39).
- 05
The login-wall trade-off
More personalization, ad signals and protection from scraping; potentially less reach. Q4 tests start outside the US. Conversion rates remain unknown. (Call audio 28:34–29:41 · 56:01–57:06).
- 06
Own the daily habit
Better feeds and app retention—not a Google rebound—are the plan. Licensing talks continue; no new agreement was announced. (Call audio 38:39–39:25 · 59:11–59:50).
Our interpretation
Podiru interpretation: discovery dependence is the risk; habitual use is the proposed defense. Management’s Google explanations remain hypotheses, while the monetizing core is still growing.
Sources & context
Based on a complete review of our timestamped transcription of the 61:29.4 public Quartr call recording, including prepared remarks, final Q&A and closing, cross-checked against the official 11-page financial release. Quartr audio is a reputable third-party recording, not an official company transcript. Timestamps refer to that audio, not YouTube.
- Official earnings release and financial tables ↗
- Official 11-page financial release PDF ↗
- Complete public earnings-call recording supplied by Quartr ↗
- Google’s AI-search and translated-page ranking effects are management hypotheses, not a verified breakdown of Google’s systems. Reddit says it lacks visibility into those changes.
- October’s decline of over 1 million referrals per week is not total referral volume or a count of distinct lost people. If that pace persists, management said Q4 average daily active uniques could decline a low-double-digit percentage from roughly 130 million; this is conditional, not a reported Q4 outcome.
- Logged-in and app cohorts overlap; their monetization shares must not be added. Management says this core grew sequentially and accounts for over 80% of monetization.
- The login-wall trade-off remains unresolved: non-US tests were planned for Q4, conversion rates were unknown, and this was not a completed worldwide rollout.
- Q3 revenue is USD GAAP actual, with growth measured year over year. Licensing discussions were continuing; no new agreement was announced.
Checked October 30, 2026.