THE KEY TAKEAWAYS
- 01
A record quarter
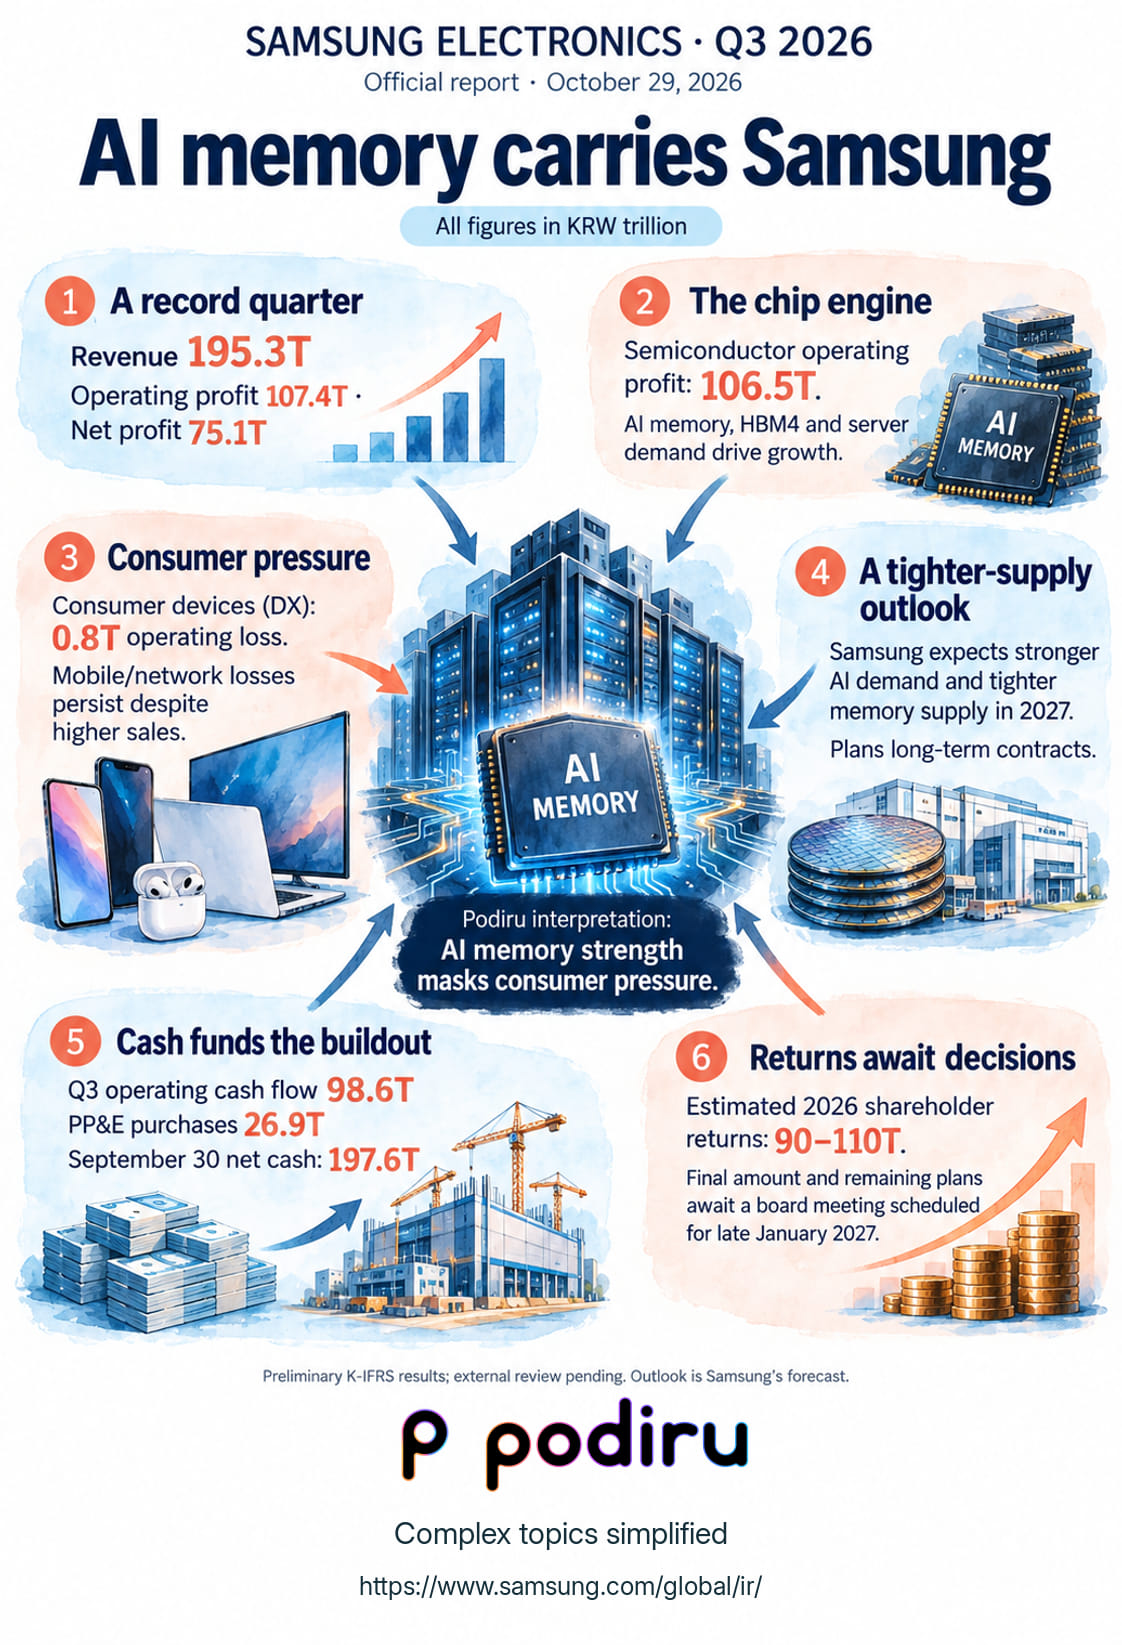
Revenue KRW 195.3T; operating profit KRW 107.4T. Net profit was KRW 75.1T. (Presentation pp. 5, 12.)
- 02
The chip engine
Semiconductor operating profit: KRW 106.5T. AI memory mix, HBM4 and server demand drove growth. (Presentation pp. 6, 7.)
- 03
Consumers still squeeze margins
Consumer devices (DX): KRW 0.8T operating loss. Mobile/network losses persisted despite higher sales. (Presentation pp. 6, 10, 13.)
- 04
A supply-constrained outlook
Samsung expects stronger AI demand and tighter memory supply in 2027, and plans long-term contracts. This is its forecast. (Presentation pp. 7.)
- 05
Cash funds the buildout
Q3 operating cash flow KRW 98.6T; PP&E purchases KRW 26.9T. September 30 net cash: KRW 197.6T. (Presentation pp. 15.)
- 06
Returns still need final decisions
Estimated 2026 shareholder returns: KRW 90–110T. Final amount and remaining plans await a board meeting scheduled for late January 2027. (Presentation pp. 15.)
Our interpretation
Podiru interpretation: the AI memory boom masks pressure in consumer businesses.
Sources & context
Complete official presentation reviewed, including all financial appendices. No full-call, Q&A or statutory quarterly-report review claim.
- All T figures are KRW trillion; no USD conversion.
- Preliminary K-IFRS results; external review pending.
- Segment sales include intersegment transactions; do not add them to consolidated revenue.
- 2027 demand and returns are company expectations, not guaranteed outcomes.
Checked October 30, 2026.