THE KEY TAKEAWAYS
- 01
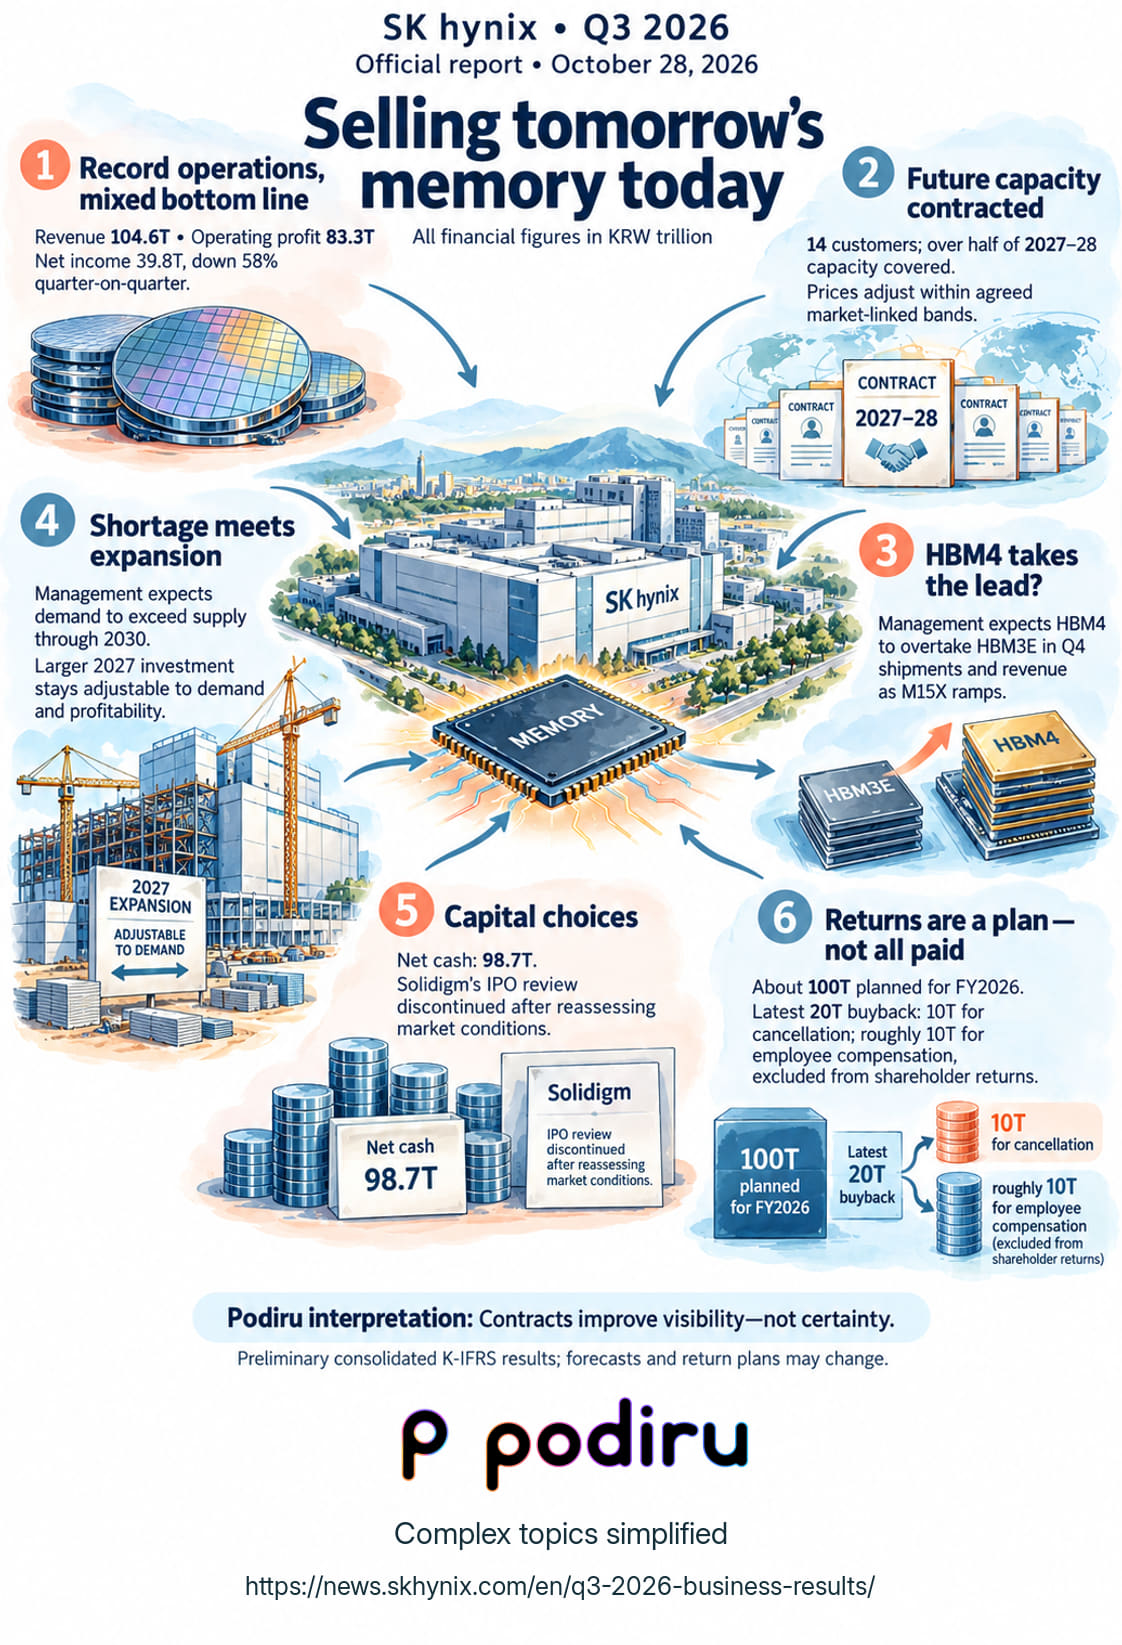
Record operations, mixed bottom line
Revenue KRW104.6T; operating profit KRW83.3T. Net income KRW39.8T fell 58% quarter-on-quarter.
- 02
Future capacity contracted
14 customers; over half of 2027–28 capacity covered. Prices adjust within agreed market-linked bands.
- 03
HBM4 takes the lead?
Management expects HBM4 to overtake HBM3E in Q4 shipments and revenue as M15X ramps.
- 04
Shortage meets expansion
Management expects demand to exceed supply through 2030. Larger 2027 investment remains adjustable to demand and profitability.
- 05
Capital choices
Net cash: KRW98.7T. Solidigm’s IPO review was discontinued after management reassessed market conditions.
- 06
Returns are a plan—not all paid
About KRW100T planned for FY2026. Of the latest KRW20T buyback, KRW10T is for cancellation; roughly KRW10T for employee compensation is excluded from shareholder returns.
Our interpretation
Contracts improve visibility—not certainty.
Sources & context
Complete official written earnings release and financial table; not a call or transcript review.
- T = trillion won. Preliminary consolidated K-IFRS results; forecasts and return plans may change.
- Operating profit and net income are different measures. The 58% net-income decline is quarter-on-quarter, not year-on-year.
- Capacity coverage and HBM4 outlook are management statements, not guaranteed future results. Contract prices remain market-linked.
- Planned shareholder returns are not all paid. The employee-compensation portion of the latest buyback is excluded from shareholder returns.
Checked October 30, 2026.