THE KEY TAKEAWAYS
- 01
More activity feeds the network
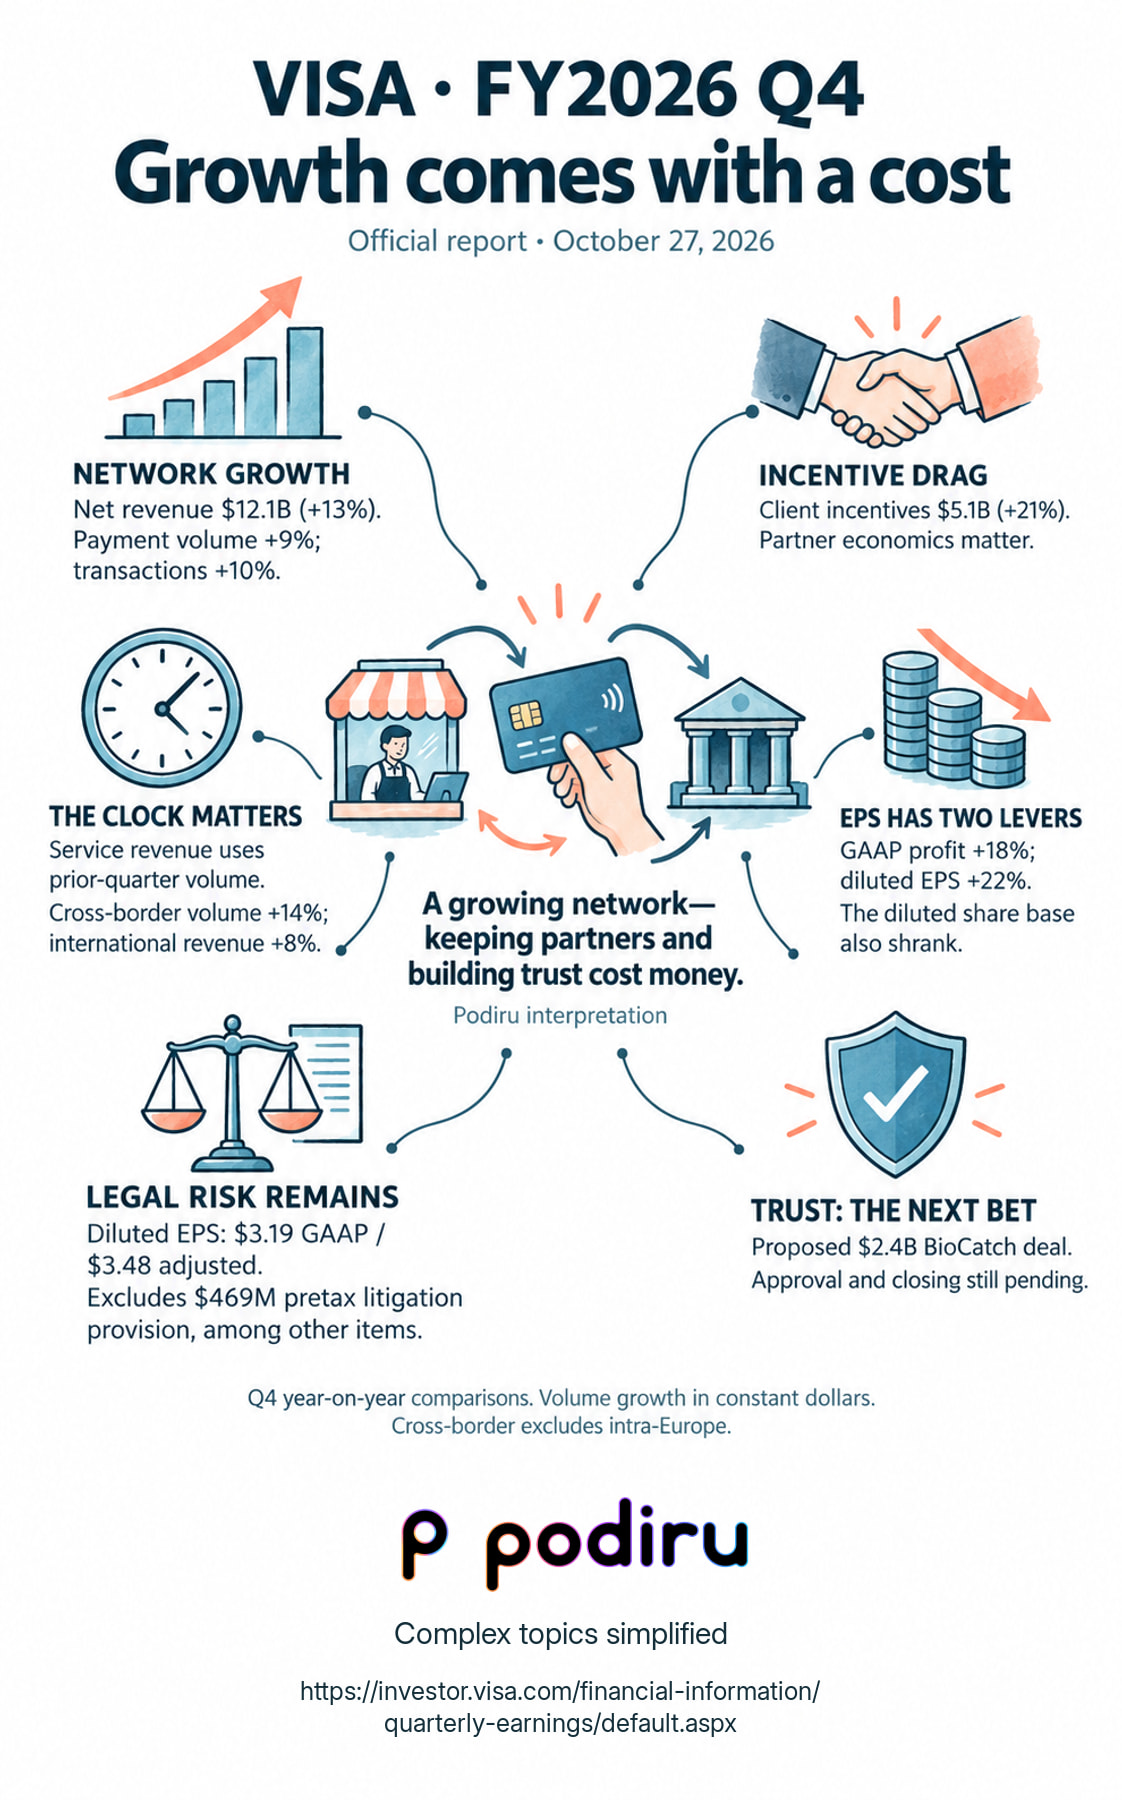
Q4 payments volume +9%; processed transactions +10%. Net revenue reached $12.1B, up 13%.
- 02
Not every dollar stays
Q4 client incentives rose 21% to $5.1B—faster than net revenue. Partner economics matter, not just payment growth.
- 03
The clock matters
Service revenue uses prior-quarter payments volume. Cross-border volume ex-intra-Europe rose 14%, but international revenue grew 8%.
- 04
EPS grows faster than profit
Q4 GAAP net income +18%; diluted EPS +22%. A smaller diluted share base helps explain the gap.
- 05
Adjustments do not erase risk
Q4 diluted EPS: $3.19 GAAP / $3.48 adjusted. Multiple adjustments include $469M of pretax litigation provision; legal exposure remains.
- 06
Trust is a bet, not a result
Management calls trust its next growth vector. Proposed $2.4B BioCatch deal adds fraud capabilities—subject to approval and closing.
Our interpretation
A growing payments network—but keeping partners and expanding trust cost money.
Sources & context
Complete official SEC Exhibit 99.1 written report and financial tables reviewed. No earnings-call or audio-review claim. Financial statements are unaudited.
- All figures shown are Q4, not full-year results, in USD. Growth comparisons are year over year; volume growth is in constant dollars. Cross-border volume excludes intra-Europe.
- Client incentives are deducted in arriving at net revenue; they are not all new cash payments. Service revenue uses prior-quarter payments volume.
- Adjusted EPS excludes multiple items, not only litigation. The $469M excluded litigation provision is pretax, distinct from $474M total litigation expense. Legal exposure remains.
- The BioCatch acquisition is proposed, not closed; regulatory approval and closing remain pending. Management’s trust strategy is forward-looking, not proven future growth.
- No quantitative FY2027 guidance is supplied by this release.
Checked October 30, 2026.